Cashless Ayurveda Hospitalisation: Documents Checklist Before Admission
Cashless Ayurveda hospitalisation requires more than showing an insurance card at the hospital. The patient’s policy must include applicable AYUSH benefits, the hospital must be eligible under the insurer’s process, and the insurer or Third-Party Administrator must approve the pre-authorisation request.
Correct and consistent documents help the insurer assess the request. However, submitting every document does not guarantee cashless approval. The final decision depends on the policy terms, medical necessity, waiting periods, exclusions, financial limits and insurer or TPA assessment.
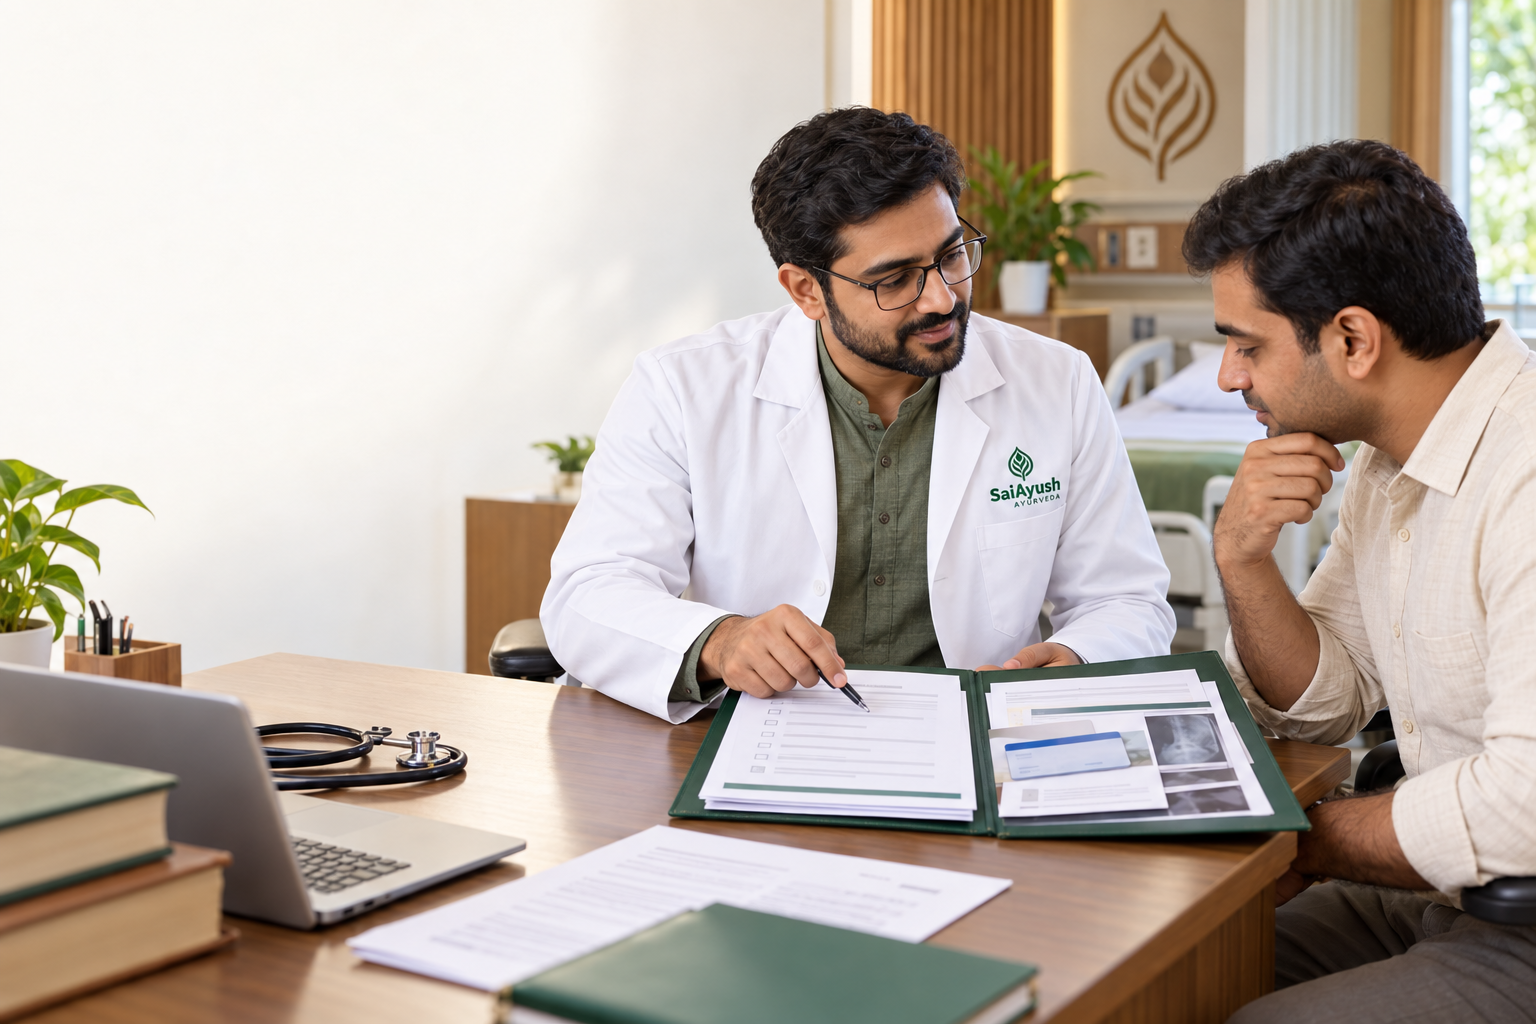
This checklist can help patients and caregivers prepare for a planned Ayurveda hospital admission.
Quick reminder: Cashless treatment means the insurer directly settles the approved portion of eligible expenses with the hospital. It does not necessarily mean that the entire hospital bill will be paid.
Quick cashless Ayurveda document checklist
Before visiting the hospital, keep the following documents ready:
- Health insurance card or e-card
- Complete health insurance policy document
- Current policy schedule
- Government-issued photo identification
- Proof of relationship for a dependent patient, if required
- Employee or corporate insurance details, where applicable
- Recent doctor’s consultation note
- Provisional diagnosis
- Proposed inpatient treatment plan
- Previous prescriptions
- Relevant laboratory reports
- Imaging reports and scans, where applicable
- Previous hospital discharge summaries
- Current list of medicines
- Details of allergies and existing health conditions
- Insurer or TPA contact details
- Previous claim information, if relevant
- Completed pre-authorisation form
- Hospital treatment estimate
- Passport-size photograph, if requested
- Any additional document requested by the insurer or TPA
Requirements differ between insurers and policies. Confirm the exact checklist with the hospital insurance desk and your insurer before admission.
First check whether your policy includes AYUSH coverage
Document preparation should begin only after checking the policy’s AYUSH provisions.
Review the policy document for terms such as:
- AYUSH treatment
- Ayurveda treatment
- Alternative systems of medicine
- Inpatient hospitalisation
- Daycare treatment
- Network hospital
- Cashless facility
- Pre-authorisation
- Co-payment
- Deductible
- Room-rent limit
- Disease-specific sub-limit
- Waiting period
- Permanent exclusions
- Non-payable expenses
If you are unsure whether your policy includes Ayurveda, read our guide on health insurance coverage for Ayurveda treatment.
Do not rely only on a health card or an insurer’s marketing brochure. The complete policy wording, schedule and endorsements determine the applicable benefits and conditions.
Documents proving insurance eligibility
1. Health insurance card or e-card
Carry the physical card or a clearly readable digital copy. It generally contains important information such as:
- Policyholder’s name
- Patient or member ID
- Policy number
- Insurer’s name
- TPA details
- Validity information
Check that the patient’s name on the card matches the identity document and hospital registration record.
2. Current policy schedule
The policy schedule normally identifies:
- Insured members
- Policy period
- Sum insured
- Product name
- Add-ons or riders
- Co-payment conditions
- Deductible information
Bring the current schedule—not an expired schedule from a previous policy year.
3. Complete policy wording
The insurance card alone may not show the conditions governing AYUSH treatment. Keep a digital or printed copy of the complete policy wording so that the relevant sections can be reviewed.
4. Corporate insurance details
Patients covered through an employer may also need:
- Employee identification card
- Corporate policy number
- Employee code
- E-card downloaded from the corporate insurance portal
- HR or benefits-desk contact
- Dependent-enrolment confirmation
Corporate policies may have benefits or restrictions that differ from individually purchased policies.
5. Proof of continuous coverage
Where a waiting period or continuity benefit is relevant, the insurer may ask for:
- Previous policy schedules
- Renewal receipts
- Portability documents
- Continuity certificate
- Earlier insurer information
Provide these only when applicable or requested.
Patient identity documents
The hospital and insurer may require identity verification before processing a cashless request.
Commonly requested documents include:
- Aadhaar card
- Passport
- Driving licence
- Voter identification card
- PAN card, where required
- Recent photograph
The name, age, gender and date of birth should be consistent across the identity document, insurance policy and hospital records.
If there is a spelling difference or changed surname, carry an appropriate supporting document. Inform the insurance desk before submission instead of altering any record yourself.
Documents for dependent patients
When the patient is insured as a spouse, child, parent or other eligible dependent, the insurer may request proof that the patient is included in the policy.
Depending on the case, this may include:
- Family health insurance e-card
- Dependent-enrolment confirmation
- Birth certificate
- Marriage certificate
- Employer-issued dependent record
- Government family identification document
Not every insurer requests relationship proof for every claim. Keep it available when there is any discrepancy or when requested.
Medical documents required before pre-authorisation
Cashless approval is based partly on whether the proposed hospitalisation is considered medically necessary. Medical documentation should explain the patient’s health condition and why inpatient care is being considered.
Doctor’s consultation note
The consultation note should record relevant information such as:
- Presenting symptoms
- Duration of symptoms
- Clinical history
- Relevant examination findings
- Provisional or confirmed diagnosis
- Previous treatment
- Current medicines
- Proposed plan of care
- Reason inpatient admission is being considered
The treating doctor—not the patient or insurer—must decide whether inpatient Ayurveda care is clinically appropriate.
Diagnostic reports
Relevant reports may include:
- Blood-test reports
- X-ray reports
- MRI or CT reports
- Ultrasound reports
- Nerve-conduction studies
- Previous specialist assessments
- Physiotherapy assessments
- Other condition-specific investigations
Only reports relevant to the present condition should be submitted unless the insurer requests the complete medical history.
Previous prescriptions
Bring prescriptions showing:
- Medicines currently being taken
- Previous treatment for the condition
- Dosage and duration
- Treating doctor’s details
- Changes made to medication
Patients should not stop prescribed medicines while waiting for an Ayurveda admission or insurance decision unless the prescribing doctor advises them to do so.
Previous discharge summaries
If the patient has previously been hospitalised for the same or a related condition, the insurer may request earlier discharge summaries.
These documents help establish:
- Previous diagnosis
- Treatment already received
- Duration of the condition
- Previous procedures
- Follow-up recommendations
- Relevant complications
Referral letter
A referral letter may be requested in some circumstances, but it is not universally required under every policy.
If another doctor has referred the patient, carry the signed referral note and relevant medical records. Do not obtain or create a referral merely for insurance purposes.
The proposed Ayurveda treatment plan
After examining the patient, the Ayurveda physician may prepare a proposed clinical plan for the pre-authorisation request.
It may contain:
- Provisional diagnosis
- Reason for admission
- Proposed duration of hospitalisation
- Physician-selected procedures
- Internal medicines, where prescribed
- Monitoring requirements
- Supportive physiotherapy or naturopathy, where clinically advised
- Expected treatment schedule
- Estimated hospital expenses
The final plan may change according to the patient’s clinical response. Such changes should be documented and communicated to the insurer where required.
Insurance eligibility should never determine which therapy is selected. Treatment must remain based on the physician’s assessment.
The cashless pre-authorisation form
For cashless admission, the hospital ordinarily sends a pre-authorisation request to the insurer or TPA.
The form commonly includes sections for:
- Patient information
- Policy and member details
- Medical history
- Diagnosis
- Proposed admission date
- Treatment plan
- Expected duration of stay
- Estimated costs
- Treating physician’s declaration
- Hospital details
- Patient or policyholder declaration
The patient should read the declaration before signing it. All information should be complete and accurate.
Never conceal a known health condition, alter medical records or provide inconsistent information. The insurer may request clarification or additional documents.
Hospital documents submitted with the request
The hospital insurance team may attach supporting institutional and clinical documents, depending on the insurer’s requirements.
These may include:
- Hospital registration details
- ROHINI information
- Applicable accreditation details
- Treating physician’s credentials
- Clinical assessment
- Proposed treatment chart
- Hospital estimate
- Pre-authorisation request
- Insurer or TPA-specific forms
Patients are generally not expected to prepare hospital registration documents themselves.
At Sai Ayush, planned insurance-supported inpatient care is handled through the KPHB Ayurveda hospital. The Madinaguda branch is an outpatient clinic and should not be treated as an inpatient cashless-admission location.
Review the hospital estimate carefully
The estimate sent for pre-authorisation may include:
- Room charges
- Doctor’s charges
- Nursing charges
- Therapy or procedure charges
- Medicines
- Investigations
- Physiotherapy, where advised
- Other eligible hospital services
The estimate is not the final bill. Actual expenses can vary according to the duration of stay, clinical requirements and policy restrictions.
Ask the insurance desk whether the policy contains:
- Room-rent restrictions
- AYUSH sub-limits
- Co-payment
- Deductible
- Disease-specific caps
- Non-medical exclusions
- Proportionate deductions
- Limits on medicines or consumables
What happens after the documents are submitted?
The insurer or TPA may:
- Approve the request
- Approve a limited amount
- Request additional information
- Ask for clarification from the doctor
- Request further investigation reports
- Keep the request pending
- Decline the cashless request
Do not assume approval until the hospital receives written authorisation.
If additional documents are requested, respond through the hospital insurance desk as promptly and accurately as possible.
Documents to review after pre-authorisation
If the cashless request is approved, review the authorisation letter for:
- Approved amount
- Approved duration
- Room category, where stated
- Co-payment
- Deductible
- Conditions attached to approval
- Expenses not authorised
- Requirement for further approval
- Validity of the authorisation
Initial approval is not necessarily the final settlement amount. The insurer may reassess the claim after receiving the final bill and discharge documents.
Documents maintained during hospitalisation
During an inpatient stay, the hospital may maintain:
- Admission assessment
- Physician’s orders
- Daily progress notes
- Vital-sign records
- Nursing records
- Therapy charts
- Medicine records
- Investigation reports
- Diet instructions
- Consent forms
- Referral or specialist notes
- Discharge planning records
Accurate daily documentation is important because the insurer may review whether the treatment provided corresponds with the diagnosis and authorised plan.
Documents required at discharge
The hospital may submit or provide documents such as:
- Final hospital bill
- Itemised bill
- Payment receipts for patient-paid amounts
- Discharge summary
- Final diagnosis
- Treatment summary
- Daily therapy chart
- Medicine bills
- Investigation reports
- Final insurer query responses
- Patient identification confirmation
- Signed discharge documentation
Before leaving the hospital, ask for copies of important clinical and billing records.
Why might the patient still need to pay?
Cashless approval does not necessarily cover every expense.
The patient may remain responsible for:
- Co-payment
- Deductible
- Non-medical expenses
- Registration charges, where excluded
- Personal convenience items
- Charges above the permitted room category
- Expenses exceeding the approved amount
- Services outside the policy
- Take-home medicines, where excluded
- Unauthorised extension of hospital stay
- Amounts exceeding the available sum insured
Ask for an explanation of patient-payable expenses before discharge.
What if the cashless request is not approved?
A cashless denial means that direct settlement was not approved under the submitted circumstances. It does not necessarily mean that the treatment is medically inappropriate.
Depending on the policy, the patient may be able to:
- Provide additional documents
- Respond to an insurer query
- Request reconsideration
- Proceed as a self-paying patient
- Submit a reimbursement claim later
Reimbursement is not guaranteed merely because cashless authorisation was declined. It will be assessed separately according to the policy.
For the reimbursement process, use a separate guide rather than expanding this cashless checklist. This keeps the purpose of this article clear and avoids confusion between the two claim methods.
Planned admission versus emergency admission
Planned admission
For planned hospitalisation:
- Contact the hospital insurance desk in advance
- Complete the physician’s consultation
- Keep the policy and identity records ready
- Submit the requested pre-authorisation documents
- Wait for written authorisation where possible
- Understand the approved amount and patient-payable expenses
Emergency admission
Emergency treatment should not be delayed while arranging insurance documents.
Go to an appropriate emergency hospital immediately for symptoms such as:
- Chest pain
- Sudden weakness or difficulty speaking
- Severe breathlessness
- Loss of consciousness
- Uncontrolled bleeding
- Seizures
- Major injury
- Sudden confusion
Sai Ayush provides planned, doctor-guided Ayurveda care and is not a substitute for an emergency department or critical-care facility.
Common documentation mistakes to avoid
Avoid these preventable problems:
- Bringing an expired insurance card
- Providing an old policy schedule
- Name differences across documents
- Missing dependent-enrolment details
- Incomplete medical history
- Missing previous discharge summaries
- Unclear photographs or scans
- Unsigned forms
- Incorrect phone number
- Inconsistent diagnosis across forms
- Assuming that an insurance card guarantees AYUSH coverage
- Beginning planned treatment before verification
- Confusing wellness packages with medically necessary hospital treatment
- Assuming that pre-authorisation covers the complete final bill
Check all documents before submission and retain copies.
Cashless Ayurveda document support at Sai Ayush
Sai Ayush Ayurveda Hospital provides preliminary policy verification and documentation assistance for eligible, doctor-guided inpatient Ayurveda care at its KPHB hospital.
The insurance-support process may include:
- Review of available policy information
- Verification of the current operational network status
- Collection of patient and policy documents
- Preparation of the proposed treatment estimate
- Pre-authorisation assistance where available
- Clinical and therapy documentation
- Itemised billing
- Discharge documentation
- Communication of insurer or TPA queries
Patients can review the current Sai Ayush cashless and reimbursement support process or contact the hospital team before a planned admission.
Hospital documentation assistance, GIC empanelment, ROHINI registration or submission of a pre-authorisation request does not guarantee approval.
Frequently asked questions
Is an insurance card enough for cashless Ayurveda treatment?
No. The policy must contain applicable AYUSH benefits, and the insurer or TPA must assess the pre-authorisation request. Medical and hospital documents will also be required.
Should I carry the complete policy document?
Yes. The policy schedule and full policy wording help verify AYUSH benefits, exclusions, waiting periods, co-payments and financial limits.
Is Aadhaar mandatory?
A government-issued identity document is generally required, but the acceptable documents may vary. Confirm the insurer’s current requirements.
Do I need original medical reports?
Carry originals where available and keep clear copies. The hospital or insurer may accept scanned records for initial review but request originals or certified documents later.
Is a doctor’s referral compulsory?
Not under every policy. A referral may be required in particular circumstances. The treating physician’s assessment and documented reason for admission remain important.
Can the hospital guarantee cashless approval?
No. The hospital can submit the request and provide documentation, but the insurer or TPA makes the decision.
Does pre-authorisation mean the full bill is covered?
No. Approval may be limited. Co-payments, deductibles, exclusions, sub-limits and non-payable items may remain the patient’s responsibility.
Should I stop my current medicines before admission?
No. Do not stop or change prescribed medicines unless the relevant prescribing doctor advises you to do so.
Can I submit a reimbursement claim after cashless denial?
It may be possible, depending on the policy. Reimbursement is separately assessed and is not guaranteed.
Where does Sai Ayush process inpatient insurance cases?
Insurance-supported inpatient admissions are processed through the Sai Ayush KPHB hospital. Madinaguda is an outpatient clinic.
Key takeaway
Preparing the correct documents can reduce avoidable delays in a cashless Ayurveda hospitalisation request.
Keep the current policy schedule, complete policy wording, insurance card, identity proof, medical records, consultation note and relevant investigation reports ready before a planned admission. Review the pre-authorisation decision carefully and ask which expenses remain payable.
Cashless approval always remains subject to policy terms, medical necessity, hospital eligibility and insurer or TPA authorisation.
Medical and insurance disclaimer: This article is intended for general education and does not constitute medical, legal, financial or insurance advice. Document requirements and insurer processes can change. Coverage, cashless authorisation and final settlement depend on the individual policy and insurer or TPA assessment. Verify the current requirements before admission.
Medically Reviewed By
Dr. Pasalapudi Visalaanjani, B.A.M.S, MD (Kayachikitsa), Reg No: 1146/A/2016
Updated on insurance documentation reviewer